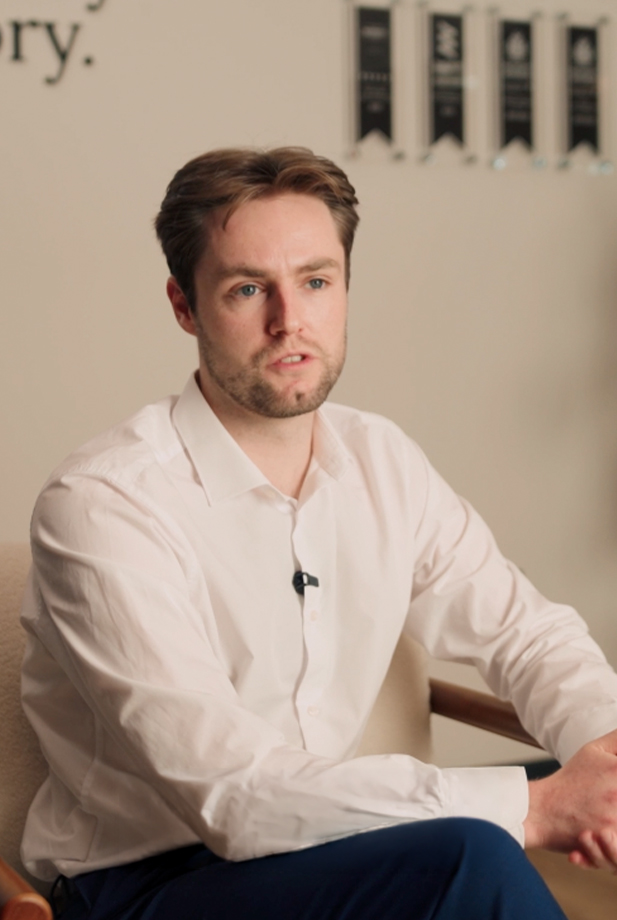
Get to know James Webster
Video highlights


James's Approach: Building custom investment strategies around individual goals and budget, James offers a complete journey to help build investor confidence.
The North West: Focusing on high-growth locations, James highlights Manchester's potential, offering unmatched growth potential and high-grade tenant profiles, maximising rental returns.
Complete Guidance & Portfolio Diversification: Access a wide spectrum of property options from £53,000 student properties to £3.5 million luxury penthouses, supported by tax experts, mortgage brokers, and short/long term letting management.

UK Property Investment Insights & Video Strategies


Frequently asked questions about UK property investment
Buying off-plan properties in Manchester can be a strong buy-to-let strategy due to the city's robust tenant demand, ongoing regeneration, and typical rental yields of 5.5% to 7%. Buying off-plan means you will be getting in below market price and receiving the best possible return.
Yes, a first-time buyer can get a buy-to-let mortgage in the UK, but the process is significantly harder. Many lenders reject first-time landlords because they are seen as higher risk, so choices are limited. To qualify, you will generally need a larger deposit (often 25–40%), a minimum personal income (typically £25,000+), strong proof of projected rental yield, and a good credit score.
Yes, you can purchase many investment properties using a mortgage, which can leverage your buying power. There may be certain opportunities, including some Purpose Built Student Accommodation, where a mortgage might not be possible. Our advisors will be able to discuss your options with you once you have an investment in mind.
Yes, you can purchase a UK buy-to-let property through a limited company, and it is a popular choice for investors around the world. In the right circumstances, it can offer significant advantages to investors.
Yes, you can transfer personal property into a limited company; however, there are things you need to bear in mind. The government classifies it as a normal market value sale from yourself as an individual to the named company. This means you will have to pay capital gains tax (CGT), Stamp Duty Land Tax and potential mortgage refinancing.
Yes, you are welcome to use your own solicitor. However, it is worth considering that our recommended solicitors will have a thorough understanding of the UK buy-to-let purchasing process and the legal requirements when investing, reducing the likelihood of any costly delays and penalties.
What our clients say
Contact us now to discuss your investment goals


Our strategic partners